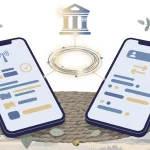
PayID uses a registered mobile number or email as a bank-transfer destination reference, while funds stay in your account until authorised.
PayID is a way to address a bank transfer using a registered identifier instead of entering a set of account details. That identifier can be a mobile phone number or an email address. In Australia, the payment system operates through the New Payments Platform (NPP), which supports transfers between participating banks.
The identifier is not itself a wallet holding your funds. Your money remains in your bank account until you authorise a payment. PayID provides the destination reference for the transfer; the NPP provides the network through which the banks can process it. This distinction helps explain why using a phone number or email address does not mean money is being sent to that phone or email service.
In a typical transfer, you select PayID as the payment method, provide the registered identifier for the destination and enter the payment amount in your banking interface. Your bank then handles the instruction through the payment system. The receiving bank routes the transfer using the identifier associated with the recipient’s account. The same basic mechanism applies when the direction of payment is reversed: the account sending the money initiates a transfer to the PayID linked to the recipient.
If you’re looking for online pokies with PayID in Australia, use this list as a starting point and check each operator’s current payment options before signing up. The details below identify what is known about each operator, but do not confirm PayID availability.
Golden Pokies
Golden Pokies is listed with a Curaçao licence. The available details do not specify its payment options.
Lucky Dreams
Lucky Dreams lists a minimum deposit of A$20 via POLi and a Curaçao licence. The available details do not confirm PayID support.
Roby Casino
Roby Casino is associated with a Curaçao eGaming licence held by Roby Games Ltd. No payment details are provided.
Uptown Pokies
Uptown Pokies is listed as operating since 2017 under a Curaçao licence, with a minimum deposit of A$20. The available details do not specify payment methods.
LevelUp Casino
LevelUp Casino lists Curaçao eGaming licence OGL/2023/174/0082, held by Dama N.V., and a minimum deposit of A$15. PayID availability is not specified.
GoldenCrown
GoldenCrown is listed with a Curaçao Gaming Control Board licence, OGL/2023/176/0095, held by Hollycorn N.V. No payment details are provided.
SkyCrown
SkyCrown lists a Tobique Gaming Commission licence and a minimum deposit of A$30. Its stated payout speeds are around 10–15 minutes for crypto and 1–5 days for fiat.
Bizzo Casino
Bizzo Casino is listed with a Curaçao Gaming Control Board licence associated with TechSolutions Group N.V. The available details do not specify payment options.
JustCasino
JustCasino is listed with a Curaçao Gaming Control Board licence. No deposit or payment details are provided.
Thor Casino
Thor Casino is listed under a Curaçao licence associated with Antillephone N.V. and Versus Odds B.V. Its stated minimum deposit is EUR 20.
The exact screens and steps depend on the bank and the payment flow being used. A casino may display an identifier for a deposit, or a payment process may direct you to your bank to make the transfer. In either case, PayID is the transfer mechanism, not the casino account itself. The casino’s internal records and your bank’s payment records are separate: one records what the casino says is credited to your account, while the other records the movement of funds between bank accounts.
This is why “PayID” does not describe every part of a payment. It identifies the method used to address and route a bank transfer. It does not, by itself, explain how a recipient processes a payment after it arrives, what account conditions apply, or whether a particular service is lawful. Those are separate questions from how the payment network works.
For a person looking up online PayID pokies, that separation matters. A payment method can function as designed without establishing anything about the service requesting a transfer. PayID’s presence does not verify a casino’s identity, the accuracy of its claims, the fairness of its games or whether it will pay winnings. Those matters cannot be inferred from the use of a bank-transfer identifier.
There is also an important Australian legal boundary. Under the Interactive Gambling Act 2001, operators are prohibited from providing real-money online casino games, including pokies, to people located in Australia. The payment mechanism does not change that rule. Explaining how PayID routes a transfer is not an endorsement of using it to fund prohibited gambling services.
At a technical level, the useful model is straightforward: the identifier points to a recipient account, your bank handles the outgoing instruction, and the NPP enables the transfer between banks. PayID replaces the need to use conventional account details in the payment address; it does not replace the banks or decide what a recipient does with incoming funds.
PayID changes how a payment is addressed and how quickly it can move between participating accounts. In an Australian payment context, you can send money using an identifier such as a mobile number or email address rather than entering a bank account number and branch code. For a payment service connected to an online casino, that can make the transfer step simpler: you select PayID, follow the payment instructions, and use the identifier provided for the transaction.
The practical difference is most visible when a deposit is credited. PayID deposits at online casinos are typically completed within seconds. That short interval can make the payment feel like part of the same online session rather than a separate task that must be completed well in advance. It does not mean every screen updates at once, however. A payment can move quickly through the banking network while the receiving service still has to register and display it in its own account system.
PayID deposits are typically completed within seconds, though the receiving service may still require time to register and display the funds in its own account system.
PayID also works in both directions. The same payment method can be used to send funds towards an account and to receive funds back, where the service supports that route. This gives the payment method a consistent role across incoming and outgoing transfers. You do not need to think of it as a deposit-only tool, although the steps and handling on the receiving service’s side may differ depending on whether money is being added or sent out.
That distinction matters because “fast payment” can describe more than one event. It may refer to how quickly a transfer is made through the payment network, how quickly the receiving account reflects it, or how quickly a service authorises an action linked to that money. Those are not necessarily the same stage. PayID can move the banking transfer quickly; it cannot make every separate account process instantaneous.
For the user, a short transfer interval can reduce waiting between initiating a payment and seeing a corresponding update. The identifier-based approach can also be easier to repeat than entering a full set of bank details each time. That convenience depends on following the instructions for the specific payment and using the correct identifier. A familiar payment name does not remove the need to check what the receiving service is asking you to do.
The same principle applies when funds move back to you. PayID’s support for transfers in both directions means that it can be part of the route for money leaving a service as well as money entering it. But the speed of the transfer mechanism should not be confused with the time a service takes to approve or prepare an outgoing payment. The payment network handles the transfer after it is initiated; decisions and processing before that point belong to the service.
This is why a claim such as “instant PayID” needs to be read narrowly. It may describe a typical deposit transfer, not every step surrounding the transaction. A fast bank transfer does not establish that an account has been reviewed, that a balance is available for withdrawal, or that a service will process an instruction immediately. It describes the movement of money, not the reliability or status of the business receiving it.
PayID itself does not make a service trustworthy, fair or legally authorised. In Australia, the Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games, including pokies, to people physically located in the country. The presence of PayID as a payment option does not change that legal position or validate an operator’s claims. This distinction is important when reading material about Australian real-money pokies and payment convenience: a working transfer method is only a payment mechanism.
So the core convenience is specific: PayID can provide a quick way to move money between participating accounts, and it supports movement in both directions. Its speed can shorten the transfer stage, while the surrounding service may still have separate steps. Keeping those stages distinct helps you understand what a payment status actually tells you, without treating a fast transfer as proof of anything beyond the transfer itself.
Legal Restriction
Under the Interactive Gambling Act 2001, it is illegal for operators to provide real-money online casino games, including pokies, to people physically located in Australia.
A PayID deposit has two separate constraints: the amount accepted by the receiving service and the amount your bank permits you to send. The first is set by the operator’s payment rules; the second is controlled by your bank. A transfer can therefore fit the casino’s stated minimum and still fail because it exceeds your available bank limit.
A specialist review describes the bank as setting the daily PayID transfer limit. Check your bank’s own app or payment information for the limit that applies to your account. Do not assume that a limit shown by another bank, or quoted for another person, will apply to you. The available amount can also be affected by transfers you have already made during the relevant day.
Minimum deposits vary between operators. The commonly stated starting range is AU$10 to AU$20, while a specialist review reports that some operators set a minimum of AU$5. Treat these as possible thresholds, not as a promise that a particular cashier will accept a given amount. The amount displayed at the payment stage is the one to check before you proceed.
The minimum is not the only condition. The transfer must be directed to the recipient details displayed for that payment, and your PayID details must correspond to the PayID registered with your bank. A mismatch can prevent the transaction from being matched or processed as intended. Read the payment instructions carefully rather than relying on a saved recipient or details copied from an earlier transaction; the payment details presented for the current transaction are what matter.
Before authorising a transfer, compare the recipient name and PayID identifier on the confirmation screen with the details supplied for the payment. Check the amount as well. If any part is unclear or differs from what you expected, stop and verify it through the relevant payment interface before confirming. This matters because a confirmed PayID transaction cannot be reversed through PayID. A mistaken recipient or amount is not corrected simply by asking your bank to cancel a completed transfer.
That irreversibility changes the order in which to act. First establish that the payment details are consistent; then enter the amount; finally review the bank’s confirmation screen before approving. Do not treat a familiar-looking name or a previous successful transfer as sufficient evidence that the current recipient is correct. Each payment should be checked on its own details.
PayID is a payment method, not a verification of the recipient’s business status or conduct. Its presence in a payment flow does not establish that a service is lawful, reliable, fair or willing to pay winnings. In Australia, the Interactive Gambling Act 2001 prohibits operators from providing real-money online casino-style services, including pokies, to people located in the country. The payment mechanism does not change that legal position.
Keep the bank-side limit, the stated deposit minimum, the registered PayID details and the displayed recipient separate in your checks. They answer different questions: whether the transfer fits your bank’s controls, whether the receiving service accepts the amount, whether your identifier matches the one held by your bank, and whether the money is being sent to the intended recipient. A successful confirmation only establishes that the transfer was authorised; it does not resolve those other questions or make a confirmed payment reversible.
A PayID option tells you something narrow: the site says it can accept or send payments through that method. It does not establish that an operator is reliable, that a withdrawal will be approved, or that a payment claim has been independently checked. Treat payment access as one operational detail, not as a verdict on the service.
That distinction matters when a page calls something the “best” PayID pokies site. A ranking can combine payment availability with opinions, promotional claims or other criteria that are not visible from the payment method itself. A position on a list does not show how the operator handles an account review, how it deals with a disputed transaction, or whether it will pay winnings. The presence of PayID cannot answer those questions.
There is also a legal limit that changes how Australian readers should interpret such claims. Under the Interactive Gambling Act 2001, providing real-money online casino games, including pokies, to people physically located in Australia is illegal for operators. A page presenting offshore real-money casino services as available to Australian residents should not be read as evidence that the service is authorised in Australia. PayID access does not alter that legal position.
A deposit and a withdrawal are different processes. A casino may list PayID as a payment method, but that does not mean a withdrawal request will be sent immediately or automatically. The casino handles its own approval process before funds leave its system. A specialist casino review reports that withdrawal handling can depend on the operator’s internal review and the player’s identity-verification status. That is a description of a reported process, not a guarantee that every operator follows the same timetable.
Processing speed can also vary between casinos. A claim that PayID is “instant” may refer to the transfer mechanism, while leaving out the time an operator takes to review a withdrawal request. Those are separate stages: the payment method moves funds after a transfer is initiated; it does not control the operator’s decision about whether or when to initiate one.
When reading a payout claim, check what event the stated time refers to. Does it begin when you submit the request, when the casino approves it, or when the transfer is sent? If the wording does not distinguish those stages, it may sound more definite than the process actually is. Do not treat a fast bank transfer as proof of fast casino approval.
Attention: A fast bank transfer does not prove that a casino has fast approval processes or that it is a reliable service.
A “PayID pokies list” can help you find pages that discuss the payment method, but a list is not itself verification. Ask what each listed claim is based on and whether it describes a specific, observable process. Statements about a payment option are narrower than claims about trustworthiness or consistent payouts. If those broader conclusions are attached to PayID availability alone, the evidence does not support the conclusion.
Look for clear distinctions between what the site says, what the payment method does and what the operator controls. PayID is a payment channel; it cannot confirm the accuracy of a casino’s promotional statements or establish how an account will be assessed. A general promise of “quick payouts” is also incomplete unless it explains whether it includes the operator’s review period. Where the page gives no process details, avoid filling the gaps with assumptions.
Be cautious with rankings that present a single winner without explaining their basis. A ranking may reflect editorial choices rather than a measured comparison of payout handling. Even a detailed description of a payment feature cannot establish fair game outcomes, transparent return information or willingness to honour a withdrawal. Those are separate matters and cannot be inferred from the presence of PayID.
For any payment claim, identify the precise fact being asserted. “PayID is available” is a claim about a payment option. “A withdrawal is processed quickly” concerns the operator’s handling as well as the transfer. “This is the best site” is a broad judgement that needs evidence beyond payment access. Keeping those claims separate makes it easier to spot when a page moves from a verifiable feature to an unsupported endorsement.
Do not use a ranking to resolve questions it cannot answer. PayID does not certify an operator, and payment availability does not show that a real-money casino service may lawfully be provided to Australians. In this market, that legal distinction is fundamental: a payment method is not a licence, a regulatory approval or a guarantee of payout.
A site’s payment page is the place to check whether PayID is actually offered. A logo or mention elsewhere on the site is not the same as a working option in the cashier: payment methods can differ by account, location or transaction type. If PayID is absent from the deposit options shown to you, do not assume that a general claim about PayID means it is available for your transaction.
Read the cashier’s displayed terms alongside the payment method. Check the minimum deposit, any stated fees and whether the page distinguishes deposits from withdrawals. PayID itself does not impose a transfer fee, but that does not establish that a particular venue charges no separate fee. A specialist review reports minimums of $10 to $30 AUD at reputable sites that accept PayID; treat that as a reported range, not a guarantee for an individual cashier.
Most importantly, a PayID listing tells you only that the site presents PayID as a payment option. It does not establish that the operator is licensed, that its games are fair, or that it will pay winnings. Payment access cannot verify those matters.
There is also a legal distinction in Australia: under the Interactive Gambling Act 2001, it is illegal for operators to provide real-money online casino games, including pokies, to people physically located in Australia. A cashier page offering PayID does not alter that position or make the service lawful.
So the cashier check is a narrow one: it can confirm what payment method the page displays and what conditions the operator attaches to it. It cannot validate the operator or turn a payment claim into evidence of reliability. Treat claims about PayID partnerships or availability as claims about payment access only, not as proof of approval, protection or payout performance.
A declined transfer does not necessarily mean PayID is unavailable or that the recipient’s payment details are incorrect. A specialist review reports that some Australian banks, including banks among the Big Four, have at times blocked PayID transfers to merchants they identify as gambling businesses. The review attributes this to banks’ acceptable use policies. This is a reported possibility, not a rule that applies to every bank or every payment.
The distinction matters: PayID is the transfer method, while the bank decides whether to let a particular payment proceed. If a transfer is refused, check the message shown by your banking app and ask your bank whether its policy caused the block. A bank can clarify its own decision; the payment method cannot override it. Repeatedly submitting the same payment is unlikely to clarify the reason and may leave you unsure which attempt, if any, was processed.
Do not treat another payment route as a way to bypass a bank restriction. A blocked payment is a bank-side decision, not proof that a gambling merchant is lawful, reliable or willing to pay winnings. PayID access cannot establish any of those things.
There is also an important Australian legal context. Under the Interactive Gambling Act 2001, providing real-money online casino games, including pokies, to people physically located in Australia is illegal for operators. A bank restriction and the law address different issues: the bank controls whether it processes a transfer under its policies, while the Act governs the provision of the gambling service.
If your bank confirms that it has blocked the transfer, follow its guidance rather than trying to disguise the recipient or route the payment through someone else. If the decline appears unrelated to a gambling restriction, ask the bank to identify the issue before taking further action. This keeps the cause of the failed payment clear and avoids assuming that a different payment attempt will be accepted.
A PayID withdrawal has two separate stages: the casino’s handling of your request and the transfer to your bank account. The time shown for the transfer does not necessarily include the time the request spends awaiting casino review.
Withdrawal Process
Casino Review
The operator checks the request and account, which may take 24–72 hours.
Payment Approval
The casino authorises the payment to leave its system.
Bank Transfer
The funds are sent via PayID, typically arriving within the same day or within 12–24 hours.
After you submit a withdrawal, the casino may check the request and your account before approving it. A specialist review describes a casino-side pending period of 24–72 hours before funds leave the operator’s system. That is a reported range, not a fixed PayID processing rule; the casino’s own process determines how long a request remains pending.
Approval marks the point at which the casino authorises the payment. It does not mean the funds have already arrived. A specialist review reports that the transfer after approval can take 12–24 hours, while another account of PayID withdrawals says an approved transfer may reach the bank account within the same day. These are reported timings, not guarantees for every casino or request.
The distinction matters when you calculate the total wait. A specialist review gives a request-to-receipt estimate of 2–4 days when the casino’s pending period is included. A delay before approval is therefore different from a delay in the bank transfer itself. If the request is still marked pending, the casino has not yet completed its internal stage; if it is approved or sent, ask whether the payment has been released and when.
Check the withdrawal status and any messages in your account, then contact the casino if the request remains unresolved. Ask whether it is still under review or has been sent, rather than treating the entire wait as a PayID transfer delay. The casino’s review and your account’s KYC status can affect when approval occurs.
These timings describe reports about payment handling; they do not establish that a casino is reliable or will pay winnings. Real-money online casino services, including pokies, are prohibited for operators serving people in Australia under the Interactive Gambling Act 2001.
A bonus described as free credit is not necessarily withdrawable cash. The offer’s terms determine what you must do before any associated winnings can be withdrawn. PayID is only a payment method; using it does not remove wagering conditions or establish that a bonus is available.
A specialist review reports wagering requirements of 30x–45x the bonus amount. Treat that range as a reported condition, not a rule that applies to every offer. Check how the requirement is calculated: the terms should make clear whether it applies to the bonus alone or to a different amount, and which games or transactions count. Do not accept credit until you can understand the calculation and the conditions attached to it.
Read the full terms before activating anything. Check whether the offer expires, whether there is a maximum bet while wagering, and what happens if you do not meet the conditions. Exceeding a stated maximum bet during bonus wagering can void the bonus and associated winnings. Creating multiple accounts at the same casino can also lead to a ban or forfeiture of winnings, so do not use another account to try to access an offer again.
Exceeding the stated maximum bet during bonus wagering can void the bonus and any associated winnings.
Keep bonus credit separate from an ordinary PayID deposit in your own assessment. A deposit is a payment you initiate; bonus credit is subject to the offer’s rules. A promotion’s wording alone does not tell you whether its conditions are reasonable or whether a payment will be handled as expected.
There is also a legal distinction in Australia: the Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people physically located in the country. A bonus claim does not change that status. Do not treat an offer mentioning PayID as evidence that the service is lawful or that its terms will result in a payout.
Before creating an account or entering payment details, open the site’s cashier and check whether PayID is explicitly listed. Do not rely on a logo, a search result, an old page or a general claim that the site supports the method. Payment options can differ between sites and may change, so the cashier is the place to confirm what is currently offered.
Check the instructions shown for both deposits and withdrawals. A PayID deposit option does not, by itself, establish that PayID is available for payouts. Read any conditions attached to the method and make sure you understand which account details the cashier expects. If PayID is not listed, or the instructions are unclear, do not assume that another transfer route will be treated as PayID.
Before making a payment, compare the name on your bank account with the name on your casino profile. Your PayID details must match the PayID registered with your bank. A mismatch can prevent the payment details from being accepted and may create difficulties when funds are returned or a payout is requested. Correct profile information before proceeding rather than trying alternate names or details.
Keep the distinction clear: a cashier listing confirms only that the site says it accepts PayID. It does not verify the site’s legal status, how it handles withdrawals or whether it will pay winnings. In Australia, providing real-money online casino games to people physically located in the country is prohibited under the Interactive Gambling Act 2001. A payment option does not change that legal position.
A Facebook post or account mentioning PayID pokies is a social-media claim, not proof that an offer is genuine or that an account represents the organisation it names. PayID does not verify a Facebook profile, a promotion, or statements about a casino. The presence of PayID as a payment method also says nothing about whether an operator is licensed, whether games are fair, or whether winnings will be paid.
What PayID can establish is narrower: once a transfer is confirmed, it cannot be reversed through PayID. Treat that as a final payment action, not as a protection against a misleading claim. If a post urges you to transfer money, the fact that it includes PayID details does not validate the person who supplied them or the purpose they describe.
Do not treat screenshots, comments, or claims of successful payments as independent verification. They may show what someone says happened, but they do not change what PayID confirms. In particular, a completed transfer is not evidence that a casino will honour a later request for winnings.
There is also a separate legal issue: Australian law prohibits operators from providing real-money online casino games to people in Australia. A Facebook reference to PayID does not alter that restriction. Keep the distinction clear: social-media content makes claims; PayID processes a transfer. Neither, by itself, proves that an online casino offer is legitimate or safe.
Select PayID as the payment method, use the destination identifier provided for the payment, and enter the amount through your bank’s payment process. Check the identifier and amount before confirming, as PayID transfers cannot be reversed once confirmed.
Yes, some online casino sites accept PayID transfers. However, accepting PayID does not establish that a site is lawful or trustworthy.
PayID is a secure bank-transfer method, but it does not verify a casino’s identity, fairness or willingness to pay winnings. Transfers cannot be reversed once confirmed, so check the recipient details carefully.
No. Under the Interactive Gambling Act 2001, operators are prohibited from providing real-money online casino games, including pokies, to people located in Australia.
You cannot legally use real-money online pokies while located in Australia: operators are prohibited from providing these games under the Interactive Gambling Act 2001.
Your PayID must be registered with your bank, using an identifier such as your mobile number or email address. The details used for a payment must match the PayID registered with your bank.